
Last lesson established the work of an entry-level equity-research associate: converting public information into a tested view on a company. Before using exchange filings, market prices, or shareholding data in that workflow, it helps to know which institution actually produces or safeguards each part of the market.
In this lesson, you will build a practical map of India’s equity-market ecosystem. By the end, you should be able to distinguish the roles of SEBI, NSE, BSE, brokers, clearing corporations, depositories, and depository participants, and trace what happens after an investor presses “Buy” or “Sell” in a trading app.
A market is more than a trading app
To an investor, buying a share can look like a few taps on a mobile app. Behind that interface, several distinct institutions make the transaction possible and trustworthy. They perform different jobs:
- a broker receives and transmits the investor’s order;
- an exchange matches eligible buy and sell orders;
- a clearing corporation manages the post-trade obligations and guarantees settlement;
- a depository records and transfers securities electronically;
- SEBI regulates this system and protects market integrity.
The most useful first distinction is between market infrastructure institutions and market intermediaries.
- Market infrastructure institutions (MIIs) provide the system on which the market operates: exchanges, clearing corporations, and depositories.
- Intermediaries, such as brokers and depository participants, provide services that connect investors and companies to that infrastructure.
Start with SEBI Investor’s overview. It gives the official institutional map that this lesson will unpack.
Read this SEBI Investor guide to establish the official roles of exchanges, depositories, and SEBI’s oversight. It is particularly useful for separating trading from the later clearing and settlement stages.
Under the introductory section, read the MII overview to understand why SEBI treats this infrastructure as central to investor protection. Then, in Part I: Stock Exchanges – Driving Capital Market Efficiency, read the exchange explanation, including the “Roles of Stock Exchanges” bullets and the NSE/BSE descriptions. In Part II: Depositories – Securing Investor Assets, read the depository section, then finish with the trade sequence. As you read, label each action as order handling, matching, clearing, or settlement.
A key principle runs through the whole system:
Executing a trade is not the same as settling it.
Execution means the exchange has matched a buyer and seller at a price. Settlement is the later completion of the transfer of money and securities.
The six roles: who does what?
SEBI: regulator and market supervisor
The Securities and Exchange Board of India (SEBI) is India’s securities-market regulator. Its mandate is to protect investors, promote the development of the securities market, and regulate that market.
SEBI does not match your order, hold your shares, or decide which shares you should buy. Instead, it establishes and enforces the framework within which exchanges, brokers, depositories, listed companies, mutual funds, research analysts, and other participants operate.
Its role includes:
- registering and supervising market intermediaries such as brokers and depository participants;
- regulating market infrastructure institutions;
- setting disclosure and listing requirements for listed companies;
- addressing misconduct such as insider trading, manipulation, and fraudulent practices;
- establishing investor-protection and grievance-redressal mechanisms.
For equity research, SEBI matters because many of the disclosures and governance standards you will later analyse exist under its regulatory framework. A broker’s commentary is not equivalent to a company’s exchange filing, and neither is equivalent to a SEBI order or regulatory disclosure.
NSE and BSE: the trading venues
The National Stock Exchange of India (NSE) and BSE Ltd. (BSE) are India’s major stock exchanges. Their central purpose is the same: provide an organised, electronic marketplace where buyers and sellers can trade listed securities.
An exchange:
- receives orders from its registered trading members, usually brokers;
- uses an electronic order book to match compatible buy and sell orders;
- produces transparent, market-determined prices;
- publishes trade and market information;
- monitors trading under the regulatory framework.
The price of a listed share is not set by the company or by the exchange. It emerges from the buy and sell orders in the market. If buyers are willing to pay more than sellers are asking, transactions occur at higher prices; if selling pressure dominates, prices may fall.
The two exchanges have their own benchmark indices:
| Exchange | Benchmark index | What the index broadly represents |
|---|---|---|
| NSE | NIFTY 50 | A basket of 50 large, actively traded NSE-listed companies |
| BSE | SENSEX | A basket of 30 major BSE-listed companies |
For now, treat these indices as useful market barometers, not as “the market” itself. You will later learn what indices contain, how they differ from funds, and how to use them as performance benchmarks.
The exchange’s job ends at the trade-matching stage. It is not where your demat holdings are stored, and it does not itself guarantee that every investor receives money or shares after every trade. Those functions belong elsewhere.
Broker: the investor-facing trading intermediary
A stock broker is the regulated intermediary through whom an investor places a buy or sell order on an exchange. The broker supplies the trading interface, opens and administers the trading relationship, checks available funds or holdings, routes the order, and sends records such as trade confirmations and contract notes.
In practical terms, when you use a brokerage app:
- You choose the security, quantity, and order type.
- The broker transmits the instruction to the exchange.
- If the exchange matches the order, the broker communicates the execution back to you.
- The broker coordinates the clearing and settlement processes on your behalf, directly or through other authorised entities.
A market order seeks immediate execution at the best available market price. A limit order specifies a price condition: it should execute only if the market reaches the stated price or better.
A broker does not set the exchange price and does not become the long-term owner of the shares you buy. It is the route into the market, not the market itself.
Clearing corporation: the settlement guarantor
Once an exchange has executed a trade, the clearing corporation takes over. This is one of the most important distinctions for understanding market safety.
Suppose you buy shares from an unknown seller. You should not need to assess whether that seller will actually deliver the shares; similarly, the seller should not need to assess whether you personally will send the money. The clearing corporation stands between the two sides as the central counterparty.
Its core functions are to:
- calculate what each participant owes after trading;
- manage risk through margins, collateral, and default procedures;
- guarantee settlement of eligible exchange trades;
- arrange the obligations for the transfer of funds and securities.
In simplified language, the clearing corporation ensures that:
- a buyer who has bought securities receives them; and
- a seller who has sold securities receives the funds.
This guarantee does not mean there is no risk anywhere in the system. Rather, clearing corporations manage counterparty and settlement risk through strict rules, member obligations, collateral, and risk controls.
Depositories: electronic custody and ownership records
A depository holds securities in electronic form. In India, the two depositories are:
- National Securities Depository Limited (NSDL)
- Central Depository Services (India) Limited (CDSL)
Shares are no longer normally transferred as physical certificates. They are held in a demat account, short for dematerialised account. After settlement, securities are debited from the seller’s demat account and credited to the buyer’s demat account through depository infrastructure.
Depositories also support:
- electronic transfer of securities;
- corporate actions such as dividends, bonus shares, rights issues, and stock splits;
- pledging securities as collateral;
- ownership and transaction records.
A common misunderstanding is to say, “My broker holds my shares.” More precisely, the investor’s securities are held electronically through the depository system. The broker may also provide depository services, but it is important to distinguish the broker’s trading role from the depository’s custody and transfer role.
Depository participant: the service link to NSDL or CDSL
An investor normally interacts with a depository participant (DP) rather than directly with NSDL or CDSL. A DP is an authorised entity that provides access to depository services, including opening and maintaining a demat account.
A bank, broker, or specialised financial-services firm may act as a DP. Your broker may therefore provide both:
- a trading account, used to place exchange orders; and
- a demat account, serviced through its DP arrangement.
These accounts work together during a sale or purchase, but they serve different purposes.
A compact role map
| Institution | Main responsibility | What it does not primarily do |
|---|---|---|
| SEBI | Regulates, supervises, and protects market integrity | Match individual orders or hold investor shares |
| NSE / BSE | Provide trading platforms and match orders | Hold demat securities or guarantee settlement alone |
| Broker | Provides trading access and transmits client orders | Determine the market price of a share |
| Clearing corporation | Clears trades, manages risk, and guarantees settlement | Operate the investor’s trading app |
| NSDL / CDSL | Hold and transfer securities electronically | Match buyer and seller orders |
| Depository participant | Provides investor access to demat services | Function as the underlying depository itself |
The distinctions can feel technical because a single brokerage app can make several services appear to be one service. Professionally, however, the roles remain separate. That separation creates checks, records, and risk controls.
For the formal definitions, read the relevant short sections of BSE’s investor-education booklet.
Booklet on the Securities Market
This BSE investor-education booklet gives concise regulatory definitions of SEBI, market infrastructure institutions, clearing corporations, depositories, and depository participants.
Read the paragraph on Regulatory Framework for Securities Markets on page 2, beginning with SEBI's mandate. Then go to Market Infrastructure Institutions and Market Intermediaries in the securities market on pages 6–7. Read the exchange definition, followed by the clearing guarantee. Finish the depository paragraph on page 7, focusing on NSDL, CDSL, and the role of a DP in opening and maintaining a demat account.
Following one equity trade from order to settlement
The following illustration shows the high-level life cycle of an equity transaction.
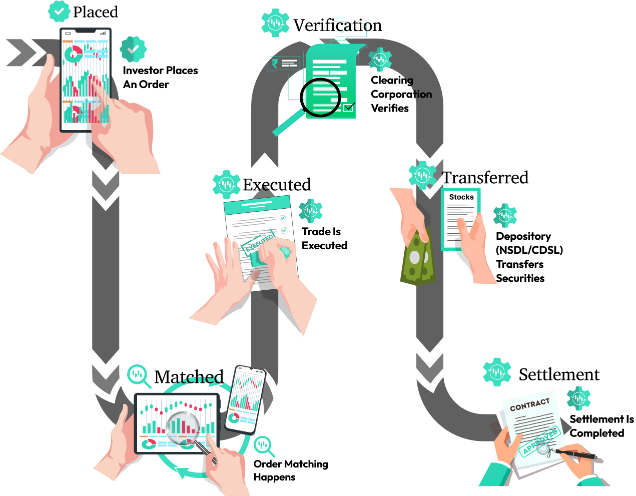
Imagine that an investor wants to buy 10 shares of a listed company through an NSE broker. The seller is unknown to the buyer; the market infrastructure makes a direct personal relationship unnecessary.
-
The investor places an order with the broker.
The investor enters the company, quantity, and order instructions through the broker’s platform. -
The broker sends the order to the exchange.
The broker acts as the investor’s authorised access point to NSE or BSE. -
The exchange matches the order.
NSE or BSE’s electronic system looks for compatible orders. If a seller is willing to sell at the buyer’s price, or a buyer accepts the available market price, the trade executes. -
The clearing corporation clears the trade.
It calculates the obligations of the relevant clearing members, manages risk, and guarantees settlement under the market rules. -
Funds and securities are settled.
Funds move through the settlement system, while securities are transferred through NSDL or CDSL infrastructure. In the usual rolling equity settlement cycle, settlement occurs on T+1, meaning one business day after the trade date. -
The buyer’s demat balance reflects the securities.
The seller’s demat account is debited and the buyer’s demat account is credited. The broker also provides the records of the transaction.
Watch this concise explanation to see the depository, clearing, broker, and SEBI roles placed in one transaction story.
Stock Market Participants (Basics) - NSE, BSE, CDSL, NSDL, Depositary Participant, Stock Broker|#11
In “Stock Market Participants (Basics),” Asset Yogi explains why an exchange, a depository, a clearing entity, and a broker are all needed even though an investor experiences the trade through one app.
Watch depositories and DPs for the distinction between where shares are electronically held and how investors access demat services. Then watch clearing and guarantee to see why a clearing corporation stands between buyer and seller. Finish with broker and SEBI, focusing on how brokers may coordinate several back-office functions while SEBI remains the overarching regulator. Treat the numerical margin example as an illustration of risk control, rather than a universal current rule.
Why this map matters for equity research
As an equity researcher, you will not normally clear trades or operate a demat account. But you need to know the institutional map because it tells you how to evaluate information and where to find it.
- NSE and BSE are important sources of company announcements, quarterly results, annual reports, corporate actions, and price or volume data.
- SEBI is the source of regulations, enforcement actions, registration information, and investor-protection rules.
- Brokers may publish research and market commentary, which can be useful secondary material but should not replace the company’s official disclosure.
- Depository-related information helps explain demat ownership and settlement mechanics; company shareholding patterns themselves are usually accessed through formal company and exchange disclosures.
- Clearing corporations explain why a visible trade price is a genuine executed transaction, but an analyst should still distinguish a trade date from final settlement and ownership transfer.
This source discipline will become practical very soon. In later lessons, you will locate annual reports, exchange filings, shareholding patterns, and corporate announcements, then create a dated source log that separates original disclosures from commentary.
Key takeaways
India’s equity market works through specialised institutions rather than one all-purpose platform:
- SEBI regulates the securities market and protects market integrity.
- NSE and BSE are exchanges that provide electronic trading and price discovery.
- Brokers give investors market access and transmit their orders.
- Clearing corporations manage post-trade obligations and guarantee settlement.
- NSDL and CDSL are depositories that hold and transfer securities electronically.
- Depository participants provide the practical demat-account service through which investors access depository infrastructure.
The central distinction is that an order is executed on an exchange, but money and securities are settled through clearing and depository systems.
Next, you will distinguish the primary market, where companies raise new capital by issuing securities, from the secondary market, where investors trade existing securities with one another.
Can't find a good explanation? Sign up and we'll make it for you
Sign up