
Welcome back. Last time, you compared four different investment claims: ownership through equity, lending through debt, a deposit claim on a bank, and units in a mutual fund. That comparison answers what you hold. This lesson answers a different practical question: who makes the Indian securities market work, and who is responsible for what?
When you tap “Buy” in an app, the app makes the process feel like a direct transaction between you and the market. In reality, a regulated network sits behind that one tap. By the end, you should be able to distinguish SEBI, NSE and BSE, brokers, clearing corporations, depositories, depository participants, and AMFI—and know where each fits when you invest or need help.
The map: rules, trading, settlement, custody, and mutual funds
A useful way to avoid confusion is to sort institutions by their primary job.
| Primary job | Main institution(s) | Plain-English role |
|---|---|---|
| Set and enforce market rules | SEBI | Regulates the securities market and seeks to protect investors |
| Match buy and sell orders | NSE and BSE | Run organized marketplaces for listed securities |
| Complete and guarantee settlement | Clearing corporations | Manage obligations and counterparty risk after a trade |
| Hold securities electronically | NSDL and CDSL | Maintain securities in dematerialized form |
| Give investors access to the depository system | Depository Participants (DPs) | Open and service demat accounts |
| Give investors access to exchanges | Stock brokers | Receive and route your orders; provide the trading interface |
| Represent the mutual-fund industry | AMFI | Promotes standards, investor awareness, and distributor registration |
The official term Market Infrastructure Institutions, or MIIs, refers to three foundational parts of the market:
- Stock exchanges
- Clearing corporations
- Depositories
They are infrastructure. A broker is an important regulated intermediary that connects you to this infrastructure, but it is not itself the exchange or the depository.
Read SEBI’s overview to establish the distinction between exchanges and depositories before attaching each name to a role.
In the opening overview, read the MII overview. Then read the section “Part I: Stock Exchanges – Driving Capital Market Efficiency,” especially the exchange explanation and the “Roles of Stock Exchanges” bullets. Continue to “Part II: Depositories – Securing Investor Assets” and read the depository explanation. Focus on the difference between trading a security and holding it.
SEBI: the regulator, not the place where you buy shares
SEBI stands for the Securities and Exchange Board of India. It is India’s securities-market regulator.
Its broad statutory purpose is to protect investors, promote the development of the securities market, and regulate that market. In practical terms, SEBI creates and enforces rules for participants such as:
- listed companies;
- stock brokers;
- stock exchanges;
- clearing corporations;
- depositories and DPs;
- mutual funds and asset-management companies;
- registered investment advisers and research analysts.
SEBI’s work includes requiring disclosures from listed companies, regulating intermediary conduct, setting market rules, supervising MIIs, investigating misconduct, and taking enforcement action where warranted. Its presence does not mean that every listed company is a good investment or that market losses will be prevented. Regulation reduces certain risks—fraud, opaque practices, unsuitable conduct—but it cannot remove business risk, valuation risk, or normal market volatility.
A good mental sentence is:
SEBI regulates the system; it does not choose investments for you or guarantee returns.
This distinction will matter later when you assess “SEBI registered” claims in advertisements. Registration may tell you that an entity is regulated in a particular capacity. It does not make a tip, product, or recommendation automatically suitable.
NSE and BSE: where orders meet
The National Stock Exchange of India (NSE) and the BSE Ltd. (BSE) are India’s major stock exchanges. Think of an exchange as a regulated electronic marketplace with a rulebook and a matching engine.
When many buyers and sellers submit orders for the same share, the exchange’s system matches compatible orders according to its rules. That continuous interaction of demand and supply produces the market price seen on your screen.
For cash-equity investing, the exchange’s core functions include:
- providing the platform on which approved members place orders;
- matching buy and sell orders;
- helping create transparent prices;
- publishing trade and market information;
- monitoring trading activity and applying exchange and SEBI rules;
- setting listing and disclosure requirements for companies on that exchange.
NSE is closely associated with the NIFTY 50 index, while BSE is closely associated with the SENSEX. You will study indices later. For now, remember that an index is a market measure; it is not the exchange itself.
What an exchange does not do
An exchange does not hold your shares in your personal demat account. It is also not usually the firm that provides your app, customer support, or investment advice. Those are functions associated with brokers, depository participants, and other intermediaries.
A company may be listed on NSE, BSE, or both. If it trades on both, each exchange has its own order book. Prices are usually very close because market participants respond quickly to differences, but the exchanges remain distinct trading venues.
Your broker: the front door to the exchange
A stock broker is a SEBI-registered intermediary and an exchange member that is permitted to execute trades on exchange platforms for clients.
Your broker typically provides:
- a trading account;
- the mobile app or web platform through which you place orders;
- order routing to NSE, BSE, or both, depending on the security and service;
- trade confirmations and contract notes;
- records, customer support, and required disclosures.
Your instruction is sent to your broker first—not directly to NSE or BSE. The broker then places the order in the exchange system under the applicable rules.
Many brokers also offer market commentary, screeners, reports, or recommendations. Treat those services separately from their execution role. A broker can be excellent at providing a low-cost, reliable platform without its research being a reason to buy a particular stock.
Use only a broker whose registration can be verified. The SEBI FAQ below gives the formal definitions, distinguishes the relevant accounts, and introduces the official grievance route.
[PDF] FAQs on Stock Broker 1. What are Market Infrastructure Institutions ...
This SEBI FAQ provides the most practical official reference for the roles of market infrastructure, brokers, accounts, and investor grievance escalation.
On page 1, read Question 1 and Question 2, including the core definitions and the broker definition. On page 2, read Question 5 and compare the three accounts through account roles. Finally, on page 9, read Question 25: begin with Level 1, continue through Level 2, and note SEBI’s role through SCORES.
The three accounts you should not mix up
A broker app may make these accounts feel like one service, but they perform different jobs:
| Account | Purpose | Usually provided through |
|---|---|---|
| Bank account | Pays for purchases and receives proceeds from sales, dividends, or redemptions | A bank |
| Trading account | Places buy and sell orders on an exchange | A stock broker |
| Demat account | Holds securities electronically after settlement | A Depository Participant connected to NSDL or CDSL |
A single financial group may offer both brokerage and DP services, so your experience may be seamless. Legally and operationally, however, the roles remain distinct.
Clearing corporations: the institution that makes a completed trade dependable
Suppose your buy order is matched with someone else’s sell order. The trade has been executed—but there is still a critical question: how can the buyer be confident of receiving shares, and the seller be confident of receiving money?
This is where a clearing corporation comes in.
A clearing corporation handles the clearing and settlement process for trades executed on an exchange. Its work includes calculating each member’s obligations, managing risk, collecting margins or collateral from members where required, and organizing the final exchange of securities and funds.
In effect, it stands between the two sides of a trade: it becomes the buyer to each seller and the seller to each buyer. This arrangement is designed to reduce counterparty risk—the risk that the other side fails to deliver shares or money.
For an investor, the crucial distinction is:
- The exchange matches the order.
- The clearing corporation handles post-trade obligations and settlement risk.
- The depository records the securities transfer electronically.
You do not usually deal with a clearing corporation directly. Your broker handles the investor-facing relationship and connects to the clearing arrangement in the background.
Stock Market Participants (Basics) - NSE, BSE, CDSL, NSDL, Depositary Participant, Stock Broker|#11
Watch Asset Yogi’s “Stock Market Participants” explanation for a visual, investor-level picture of the separation among brokers, depositories, clearinghouses, and SEBI.
Watch custody and DPs to see why shares are held through the depository system rather than at an exchange. Then watch clearing role, focusing on why clearinghouses stand between the buyer and seller. Finish with broker and SEBI for the practical point that a broker often coordinates several back-end services for a retail investor.
Depositories and DPs: where your shares are held
India’s two depositories are:
- NSDL — National Securities Depository Limited
- CDSL — Central Depository Services Limited
A depository holds securities in dematerialized, or electronic, form. Instead of receiving a physical share certificate, you hold an electronic beneficial interest recorded through the depository system.
Depositories make several everyday investor outcomes possible:
- electronic credit of shares after a purchase;
- electronic debit of shares after a sale;
- a consolidated record of your holdings;
- processing of corporate actions such as bonus shares, stock splits, and rights entitlements;
- pledging of securities as collateral, where applicable.
The Depository Participant: your access point
An investor generally accesses NSDL or CDSL through a Depository Participant, or DP. A DP may be a bank, broker, or another SEBI-registered entity authorized to offer demat services.
This gives us an important distinction:
| Question | Correct answer |
|---|---|
| Who operates the central electronic securities system? | NSDL or CDSL |
| Who opens and services your demat account? | A DP |
| Who lets you submit an order to buy or sell? | A broker |
| Who matches that order? | NSE or BSE |
| Who manages settlement obligations after the match? | A clearing corporation |
A broker may also be your DP, or it may arrange demat services through another DP. That is why one app can appear to “do everything.” The convenience is real, but understanding the underlying roles helps you check statements, identify the right complaint channel, and know where your assets are recorded.
AMFI: important for mutual funds, but not the mutual-fund regulator
AMFI stands for the Association of Mutual Funds in India. It is the mutual-fund industry association, representing SEBI-registered asset-management companies, or AMCs.
AMFI’s role includes supporting industry standards, investor awareness, professional conduct, and the framework for mutual-fund distributors. It is also associated with the AMFI Registration Number, or ARN, used by mutual-fund distributors.
Do not confuse these four entities:
| Entity | Main role |
|---|---|
| SEBI | Regulates mutual funds, AMCs, advisers, and relevant intermediaries |
| AMC / fund house | Creates and manages mutual-fund schemes |
| AMFI | Industry association for mutual funds and related standards |
| Mutual-fund distributor | Helps sell or distribute schemes and may earn commissions |
An ARN can help identify a registered mutual-fund distributor, but it is not proof that a recommendation is unbiased or right for your goals. A distributor may be paid through the fund’s distribution structure, which is one reason you will later learn to compare direct and regular mutual-fund plans.
The simplest summary is:
SEBI regulates mutual funds; AMCs manage funds; AMFI represents the industry; distributors distribute funds.
Where to go when something goes wrong
Knowing the institutional map is also investor protection. A missing credit, unauthorized transaction, incorrect charge, or dispute should not be handled merely through social-media posts or informal messages.
Start by preserving evidence: contract notes, ledger statements, order details, screenshots, emails, and dates. Then use the formal escalation route.
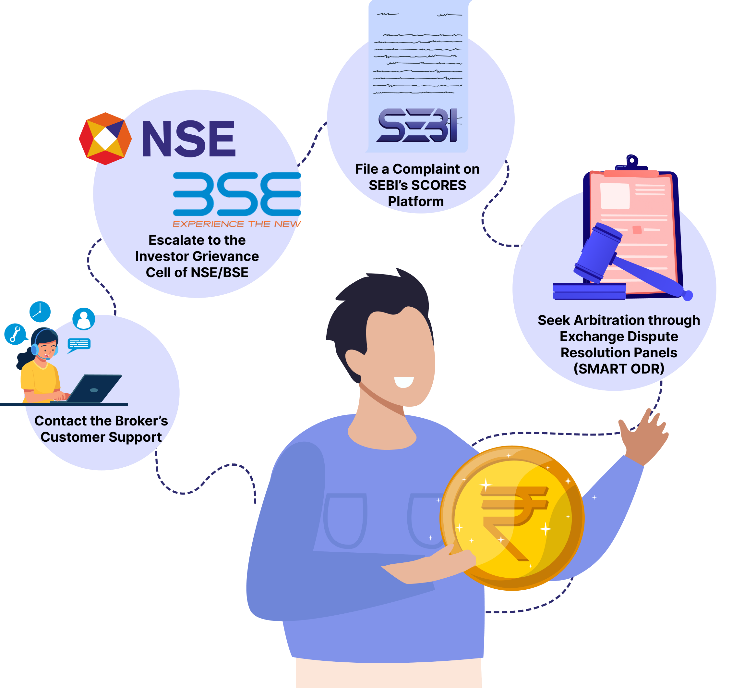
The exact sequence, timelines, and online channels can change, so use the broker’s current Investor Charter, the relevant exchange’s current instructions, and SEBI’s current SCORES guidance. The broad logic remains sound:
- Raise the issue with the broker first through its formal support and escalation process.
- If unresolved, use the relevant stock exchange’s grievance mechanism.
- Use the applicable SEBI SCORES route if the issue remains unresolved at the broker or exchange level.
- Where appropriate, exchange-level grievance committees, arbitration, or other dispute-resolution mechanisms may apply.
Do not wait until a situation becomes difficult to locate your broker’s grievance email, escalation matrix, DP details, and account statements.
One purchase, viewed through the institutional map
Imagine buying shares of a listed company for long-term investing. Without yet going into the settlement timeline, here is the high-level map:
- You place an instruction through your broker using your trading account.
- The broker routes the order to an exchange, such as NSE or BSE.
- The exchange matches it with a compatible sell order and records the trade.
- The relevant clearing corporation calculates obligations and manages settlement risk between market participants.
- The depository system, through NSDL or CDSL and the relevant DPs, records the transfer of shares into the buyer’s demat holding.
- Your bank-account funds and your securities holding are updated through the applicable settlement arrangements.
- SEBI regulates the institutions and rules surrounding the process.
AMFI is not part of this ordinary cash-equity purchase. It becomes relevant when you invest in mutual funds, where the AMC manages the scheme and AMFI is part of the broader industry framework.
Key takeaways
SEBI is India’s securities-market regulator: it sets rules, supervises participants, and supports investor protection, but it does not guarantee investment returns.
NSE and BSE are exchanges where buy and sell orders are matched. Brokers are your regulated route to those exchanges. Clearing corporations handle the obligations and risk management that help completed trades settle reliably.
NSDL and CDSL are depositories that hold securities electronically, while DPs provide your practical demat-account access. AMFI is the mutual-fund industry association; it is not a replacement for SEBI and does not manage a mutual fund’s portfolio.
The essential role map is:
- SEBI regulates
- Brokers connect
- NSE/BSE match
- Clearing corporations settle
- NSDL/CDSL hold
- AMFI represents the mutual-fund industry
Next, you will follow a cash-equity purchase or sale in more detail—from placing an order through your trading account to the final appearance of shares in your demat account.
Can't find a good explanation? Sign up and we'll make it for you
Sign up